Many businesses will operate internationally and consider the impact of consumption taxes on their prices, transactions, and responsibilities. Goods and Services Tax (GST) and Value Added Tax (VAT) are consumption taxes that may be imposed on the supply of goods and services and have several similarities, although they may also have significant differences in practice. Understanding the differences between GST and VAT helps businesses know which taxes to report and pay and prepare for the complexities involved in the new jurisdiction.
Planning to expand your business internationally? Connect with Vorx Consultancy to discuss your global business setup and compliance needs.
What Is GST?
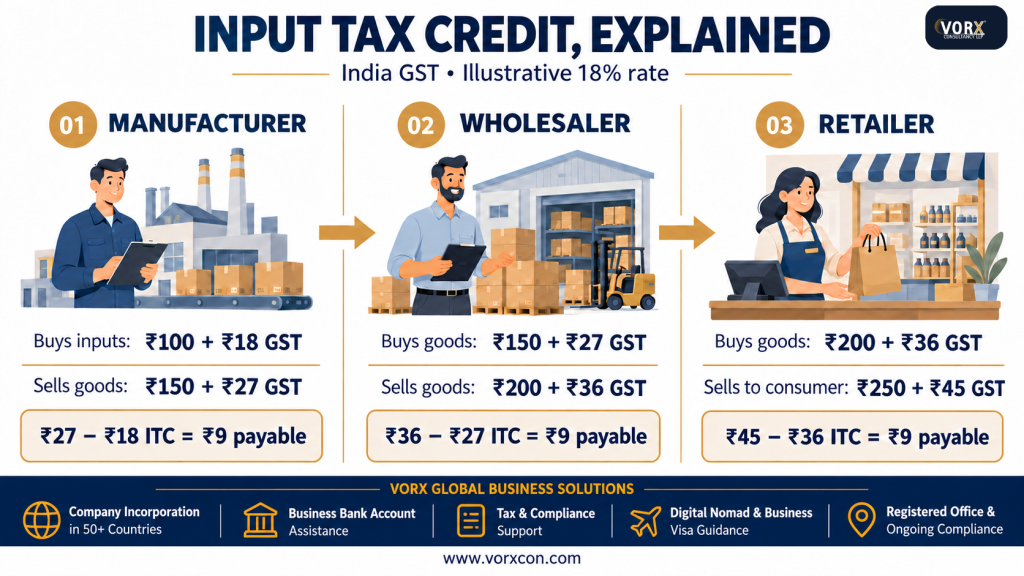
Goods and Services Tax (GST) is a consumption tax imposed on eligible supplies of goods and services. Usually, GST is charged at each stage of the supply chain, with businesses liable to report GST on their returns for the tax period. Businesses may be able to reclaim GST incurred on business purchases under most GST regimes, and input tax credits help to avoid the tax being charged more than once in the supply chain.
There are several variations of GST, with differences in the rates of tax, the types of supplies that are eligible for taxation, the activities determining a business’s registration requirements, the frequency of reporting, and the method of calculating tax on imports and exports of goods and services.
What Is VAT?
Value Added Tax (VAT) is a consumption tax charged on eligible goods and services as they move through the supply chain. Businesses generally charge VAT on taxable sales and may recover eligible VAT paid on purchases, subject to local rules.
For example, a manufacturer may pay VAT on raw materials, while a retailer pays VAT on products purchased for resale. Eligible businesses can generally deduct recoverable input VAT from the VAT due on their sales. The remaining tax is paid to the relevant authority.
VAT is designed to tax consumption while reducing the risk of tax cascading. However, exemptions, reduced rates, and recovery rules vary across countries.
Recommended Reading:
Read our International Tax Planning Guide to learn how effective tax planning can support global business operations and help manage tax responsibilities.
GST vs VAT: Key Differences
Comparison factor | GST | VAT |
Full form | Goods and Services Tax | Value Added Tax |
Tax structure | Often a unified consumption tax framework | Commonly administered as a value-added tax |
Tax rates | Vary by jurisdiction and supply category | Vary by jurisdiction and supply category |
Input tax credit | Available for eligible purchases under local rules | Available for eligible purchases under local rules |
Administration | May involve national or subnational authorities | Depends on the jurisdiction’s tax administration |
Compliance | Registration, returns, and records are required where applicable | Registration, returns, and records are required where applicable |
The key distinction is not always the tax mechanism itself. In many jurisdictions, GST is effectively a VAT-style tax under a different name. The most meaningful differences often relate to the applicable legislation, administration, and compliance requirements.
Planning to expand your business internationally? Connect with Vorx Consultancy to discuss your global business setup and compliance needs.
Similarities Between GST and VAT
GST and VAT have several important features in common:
- Consumption-based taxation: Both generally tax the consumption of eligible goods and services.
- Multi-stage collection: Tax may be collected at several stages of the supply chain.
- Input tax credits: Eligible businesses can generally recover tax paid on qualifying purchases.
- Consumer impact: The tax cost is generally borne by the final consumer, although the economic impact can vary.
- Compliance requirements: Businesses may need to register, issue compliant invoices, maintain records, and submit tax returns.
Recommended Reading:
Explore common tax mistakes businesses should avoid when expanding abroad to better prepare for international operations.
Types of Transactions Covered Under GST and VAT
The types of supplies of goods and services covered under GST and VAT will depend on the rules in each jurisdiction. However, there are several common supplies that are subject to GST and VAT.
Transactions Commonly Covered Under GST
The supply of goods: common goods that are subject to GST include the sale of equipment, furniture, and clothing.
The supply of services: common services that are subject to GST include the provision of repair services.
Import of goods: businesses must pay GST on imports of goods.
Online transactions: some jurisdictions may impose GST on online transactions.
Transactions Commonly Covered Under VAT
The supply of goods: common goods that are subject to VAT include the sale of goods by manufacturers and retailers.
The supply of services: common services that are subject to VAT include the provision of professional services such as accommodation and telecommunications.
Import of goods: businesses must pay import duty on goods.
Digital products and services: businesses must pay VAT on the supply of certain digital products and services.
What Is the Main Difference?
As GST and VAT apply to similar supplies of goods and services, the main difference between the two consumption taxes is how they are applied in practice. This difference will impact the tax liabilities of businesses supplying goods and services and purchasing goods and services for use in their operations.
Some supplies of goods and services may not be subject to GST or VAT, while others may be subject to zero-rating or reduced rates.
How GST and VAT Work: A Practical Example
Consider a hypothetical furniture manufacturer operating in a jurisdiction where the applicable GST or VAT rate is 10%.
The manufacturer purchases wood and other eligible materials for $1,000 and pays $100 in tax. It then sells finished furniture to a retailer for $2,000, charging $200 in tax.
If the manufacturer is eligible to claim the full input tax credit, its net tax payable would be:
$200 output tax − $100 input tax credit = $100 net tax payable.
The retailer may then account for tax on its own sales and claim eligible credits on its purchases. This example illustrates the general mechanism; actual calculations depend on local rules, transaction values, and credit eligibility.
How GST and VAT Affect International Businesses
As businesses enter new markets, the implications of GST and VAT must be accounted for. Taxes may affect the price of supplies and, in turn, the business’s margins, as they may be responsible for reporting and paying the taxes and will not be able to reclaim them completely. Businesses may also need to know whether they are required to register in the new jurisdiction and how frequently they must report and pay GST or VAT.
Expanding internationally may also bring new considerations for businesses, such as the rules and requirements for invoicing and records. Businesses must be aware of their tax obligations in the new jurisdiction, such as the eligibility of a supply, the rate, and the frequency of reporting.
Planning to expand your business internationally? Connect with Vorx Consultancy to discuss your global business setup and compliance needs.
Common Misconceptions About GST and VAT
- GST and VAT are completely different taxes. Not necessarily. Many GST systems operate on principles similar to VAT.
- Every business must register. Registration depends on local thresholds, business activities, and specific rules.
- All purchase tax can be claimed back. Only eligible tax may be recoverable, and restrictions can apply.
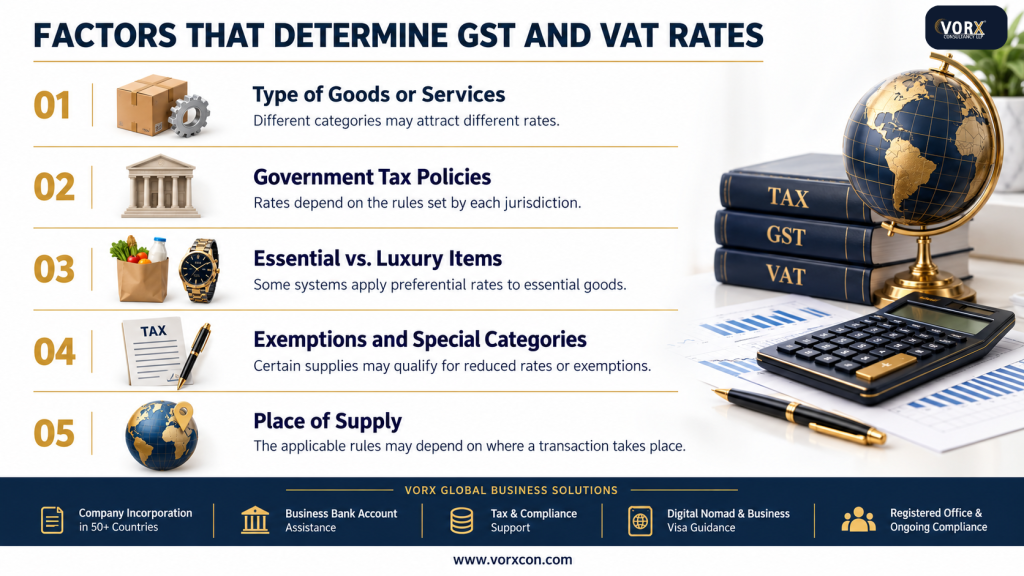
- The same tax rate applies to every product and service. Rates and exemptions may vary by supply category and jurisdiction.
- International sales are always tax-free. Cross-border transactions may qualify for special treatment, but conditions and documentation requirements apply.
How Vorx Supports Businesses with Global Tax and Compliance?
Expanding internationally is more than just incorporating or forming a company in a new jurisdiction. Businesses must also know their regulatory and compliance obligations in the new location. Vorx Consultancy offers international formation and expansion, business tax and compliance advisory, and filing support to assist businesses to know their setup and compliance obligations in new jurisdictions.
This service will help businesses identify the relevant regulatory and compliance considerations when setting up and operating a company abroad. The specific support will depend on the businesses’ needs and the relevant rules in the target jurisdiction.
Planning to expand your business internationally? Connect with Vorx Consultancy to discuss your global business setup and compliance needs.
Final Thought
GST and VAT have similar aims of imposing a tax on consumption and allowing businesses to reclaim the tax on their purchases. Their practical application will depend on the rules in the relevant jurisdiction; therefore, understanding the similarities and differences of the two sets of rules can help businesses evaluate their own tax positions and obligations in the respective jurisdictions. Knowing the similarities and differences between VAT and GST can help businesses expand internationally and take into account the considerations for their supplies and purchases of goods and services in the new jurisdiction.
