Registering an LLC in Oman is easy. Ensuring that it remains in good standing is what most foreign owners miss out on not because it’s tough, but because they have to interact with five different bodies each operating on its separate schedule.
This guide brings Oman company compliance requirements into one place: company law duties, tax filings, Omanisation and a dated calendar you can work from.
It’s written for owners of mainland companies, especially Indian founders managing an Oman entity from abroad.
These rules are based on what can be verified by October 2026. There have been many changes made, so please check the requirements before proceeding.
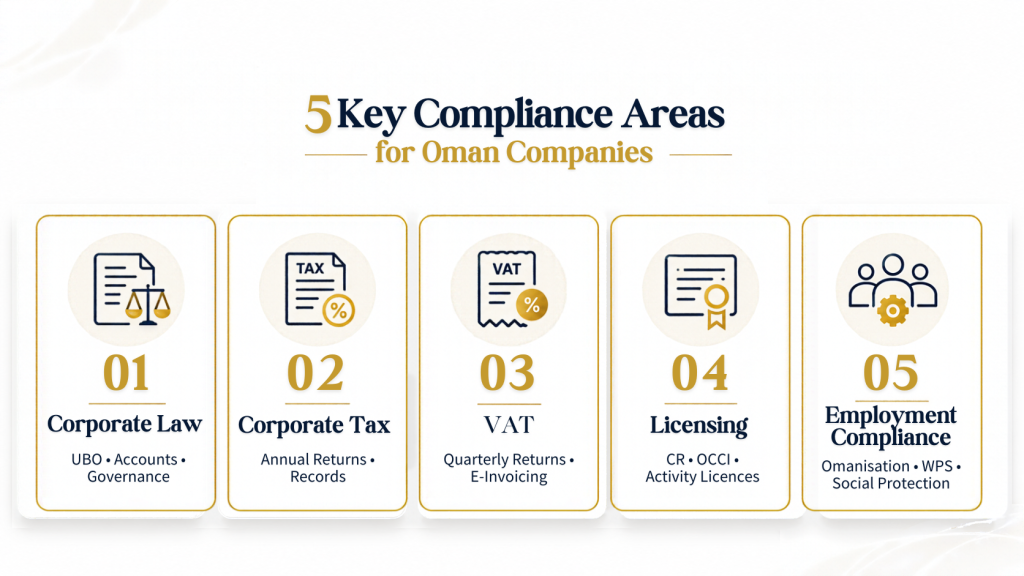
Oman Compliance at a Glance
Area | Authority | Key Requirements | Frequency |
Corporate Law | MOCIIP | UBO records, accounts, audit (if required) | Annual / Ongoing |
Corporate Tax | OTA | Tax return & financial records | Annual |
VAT | OTA | VAT returns & e-invoicing (2027) | Quarterly / Phased |
Licences | MOCIIP / OCCI | CR, membership & licence renewals | Before expiry |
Employment | Labour Ministry / SPF | Omanisation, payroll & contributions | Monthly / Ongoing |
Free zone companies follow extra zone rules; this guide covers mainland LLCs.
Corporate Law Compliance Under the Commercial Companies Law
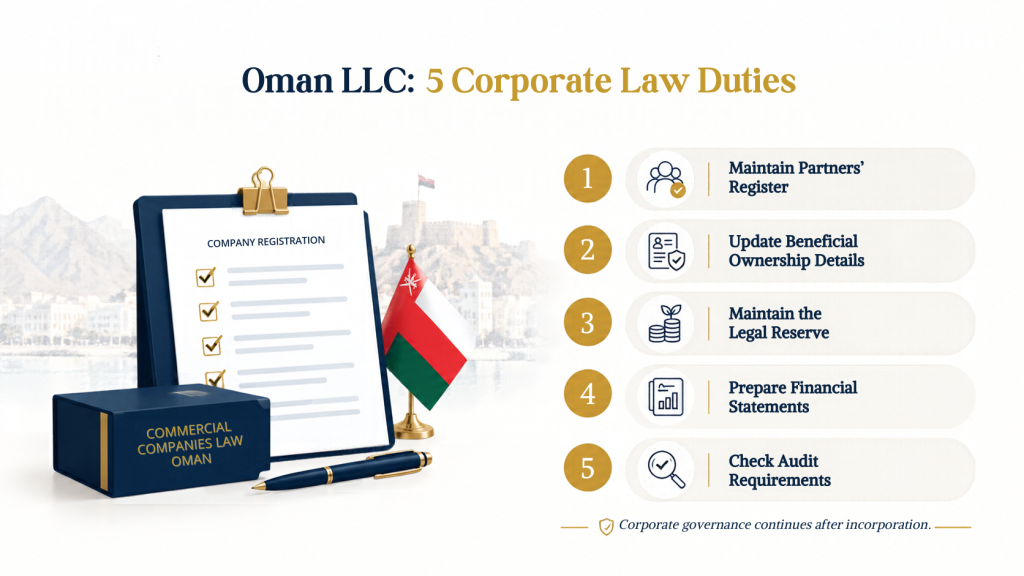
Oman’s Commercial Companies Law (Royal Decree 18/2019) sets the governance baseline. Five duties matter most.
Keep Registers and Filings Current
Your LLC must keep a partners’ register, and a partner’s ownership only counts once it’s recorded there.
Amendments to the constitutive documents – a new manager, a share transfer, an activity change must be registered within 30 days.
Maintain a Beneficial Ownership (UBO) Register
This is the duty foreign owners most often miss. Companies should have a register of their ultimate beneficial owners and update it within five working days of any change. They should also appoint an individual resident of Oman who is able to provide UBO details within three working days.
If you hold shares through a Singapore or UAE holding company, the register must look through to the individual owner.
Transfer 10% of Profit to the Legal Reserve
Each year, 10% of net profit after tax goes into a legal reserve until it equals one-third of share capital.
It can absorb losses but can’t be paid out as dividends – factor this in before promising distributions.
Prepare Accounts and Hold the Partners’ Meeting
Managers have 90 days after year end to prepare the financial statements. Within 180 days, every partner must receive them, with any auditor’s report and a call to the approval meeting. Originals must be open for inspection at the head office at least 14 days before it.
Check Whether You Need an Audit
Company law requires an auditor if the LLC has more than seven partners, capital above OMR 50,000, a clause requiring one, or a request from partners holding a fifth of the capital.
In practice, tax rules matter more: the OTA expects standard-rate taxpayers to file audited accounts with their return, so most foreign-owned LLCs need an audit anyway. Vorx offers annual compliance support if you’d rather not manage this yourself.
Oman Company Tax Filing Requirements
Corporate Income Tax
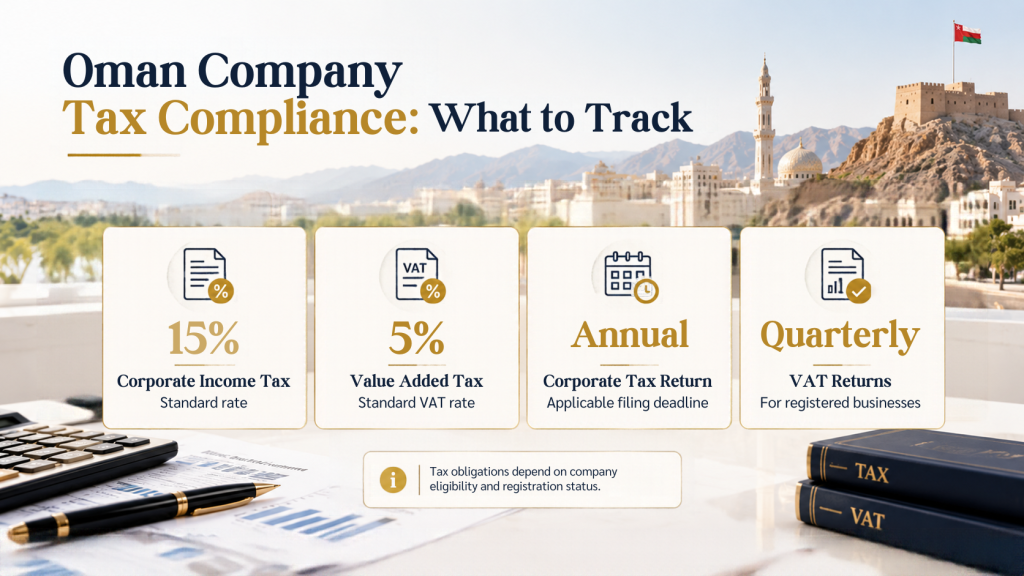
The standard rate is 15%, and resident companies are taxed on worldwide income. You complete one annual tax return with audited accounts in four months after the end of the year – 30 April if your year end is December.
Qualifying small businesses are taxed at a 3% flat rate.The conditions on capital, income, staff and activity are strict, so confirm eligibility with the OTA first.
Keep IFRS accounts, retain records for ten years, and disclose related-party transactions – including any services bought from or billed to an Indian parent.
Clean monthly accounting and bookkeeping makes the four-month deadline realistic. To compare rates, see our global corporate tax rates table.
VAT
VAT is 5%.It is compulsory for those whose taxable supplies cross the limit of OMR 38,500 in the past 12 months, or are expected to do so in the next 12 months. Voluntary registration begins from OMR 19,250.
Returns are quarterly, due with payment within 30 days of each quarter end. A missed return can cost OMR 500–5,000.
Watch the forward-looking test: one large contract can make registration mandatory before past turnover crosses the threshold. Vorx can handle your VAT registration and filings.
E-Invoicing (Fawtara): The 2027 Deadlines
Many guides are already out of date here. In August 2026, OTA Decision No. 189/2026 replaced the earlier four-phase timetable with two dates:
Annual supplies | Mandatory e-invoicing from |
Above OMR 5 million | 1 April 2027 |
OMR 5 million or less | 1 October 2027 |
After that, paper or PDF invoices won’t count as valid tax invoices. Invoices must go through OTA-accredited providers, generally within 15 days of the supply.
The OTA can grant temporary exemptions, but only to taxpayers who file and pay on time. It is estimated that most SMEs have until October 2027 – not much time when the amount of software and testing is taken into consideration. Check if your accounting software can communicate with one.
Withholding Tax on Payments Abroad
Some payments to foreign companies without an Oman presence, such as royalties and certain service fees, may require tax to be withheld.
This often catches Oman LLCs paying an Indian parent for IT or management services. Get international tax structuring advice, including on the India–Oman tax treaty, before setting up recurring payments.
Personal Income Tax From 2028
The tax rate will be 5% on income exceeding OMR 42,000 per annum from 1 January 2028.
Residents (usually 183+ days in Oman) are taxed on their worldwide income, while non-residents are taxed on their income sourced in Oman.
Owner-managers who reside in Oman and senior expatriate employees should consider their remuneration and dividends before then.
Licence and Registration Renewals
- Commercial Registration (CR): renewal through Oman Business Portal before expiration date; expired CR will prevent access to other government services.
- Membership OCCI: renewal through online process; most agencies require a valid certificate.
- Activity licences: municipal and sector licences run on their own cycles.
Keep one list of expiry dates with a named owner. An expired CR also commonly delays bank KYC reviews.
Omanisation and Employment Compliance
Omanisation Requirements for Foreign Companies
Starting from April 2024, fully owned foreign enterprises should have at least one Omani employee within one year of commencing operations and register that employee with the Social Protection Fund.
Prescribed Omanisation percentages were included in the foreign investment regulations through Ministerial Decision 411/2025, and sector quotas may demand additional employees. Budget for this from day one.
Payroll Through the Wage Protection System
Salaries must be paid through the Wage Protection System (WPS), and contracts must be updated whenever pay changes – a mismatch between contract and actual pay can be flagged even when salaries are paid on time.
Social Protection Fund Contributions
Employers pay monthly contributions, and expatriate coverage is expanding:
- Maternity and sick-leave insurance: contributions now apply to expatriate staff as these branches come into force.
- Savings scheme for expatriates: will replace end-of-service gratuity; employer contribution will be 9% of basic salary from 19 July 2027 onwards.
- Insurance for work-related injuries for expatriates who are not Omanis: to start from July 2028.
This savings scheme converts an obligation into an expense on a monthly basis; hence, include it in your budget for 2027.
Oman Annual Compliance Calendar (December Year End)
When | Requirement |
Monthly | Payroll (WPS) & social protection |
Quarterly | VAT filing within 30 days |
30 March* | Accounts & eligible 3% tax return |
30 April* | Corporate tax return |
By June* | Annual meeting & financial statements |
Within 5 working days | Update UBO details |
Before expiry | Renew CR, OCCI & licences |
April/October 2027 | E-invoicing rollout |
July 2027 | Expat savings scheme |
The timing trap: company law allows 180 days for approved accounts, but the tax return needs audited accounts in four months. Start the audit in January and plan to the tax deadline.
Is Your Oman Company Meeting All Its Compliance Deadlines?
From corporate tax filings to licence renewals, Vorx Consultancy helps foreign business owners manage their Oman compliance obligations.
Example: An Indian Founder's First Compliance Year
Hypothetical scenario for illustration only.
Priya, a Pune-based founder, owns 100% of a Muscat IT services LLC with OMR 150,000 capital and a December year end. She manages it from India.
- Audit: capital above OMR 50,000 triggers one, so she appoints an auditor in January and files tax before 30 April.
- VAT: revenue of about OMR 220,000 means quarterly VAT returns and e-invoicing from 1 October 2027.
- Group payments: her LLC pays the Indian parent, so she checks withholding tax.
- UBO and staffing: she appoints an Oman-resident UBO liaison and hires an Omani employee in year one.
None of this is difficult on its own. The risk is in the timing.
Common Mistakes Foreign Owners Make
- Planning the audit to the company-law deadline instead of the tax deadline.
- Skipping the UBO register or resident liaison.
- Missing the VAT forward-looking test after a big contract.
- Paying the overseas parent without checking withholding tax.
- Leaving the first Omani hire too late.
- Letting the CR or OCCI membership lapse because nobody owns the dates.
- Assuming e-invoicing is years away – for most SMEs it’s about 12 months out.
Final Thoughts
Oman compliance is mostly about keeping five calendars in sync. Start the audit early, keep registers current and plan Omanisation from the outset.
With e-invoicing and the expat savings scheme arriving in 2027, now is a good time to review where your company stands.
Vorx Consultancy helps foreign-owned Oman companies with annual compliance, accounting, VAT and tax filing. Book a consultation and we’ll help you build a compliance calendar for your company.
This article is general information, not legal or tax advice. Verify current rules before acting.
Keep Your Oman Company Compliant with Vorx Consultancy
Get professional support with annual filings, corporate tax, VAT, accounting and ongoing business compliance.
