Germany is Europe’s largest economy and a serious route into the EU market, which is why more Indian founders in IT, engineering, manufacturing and trading are setting up there.
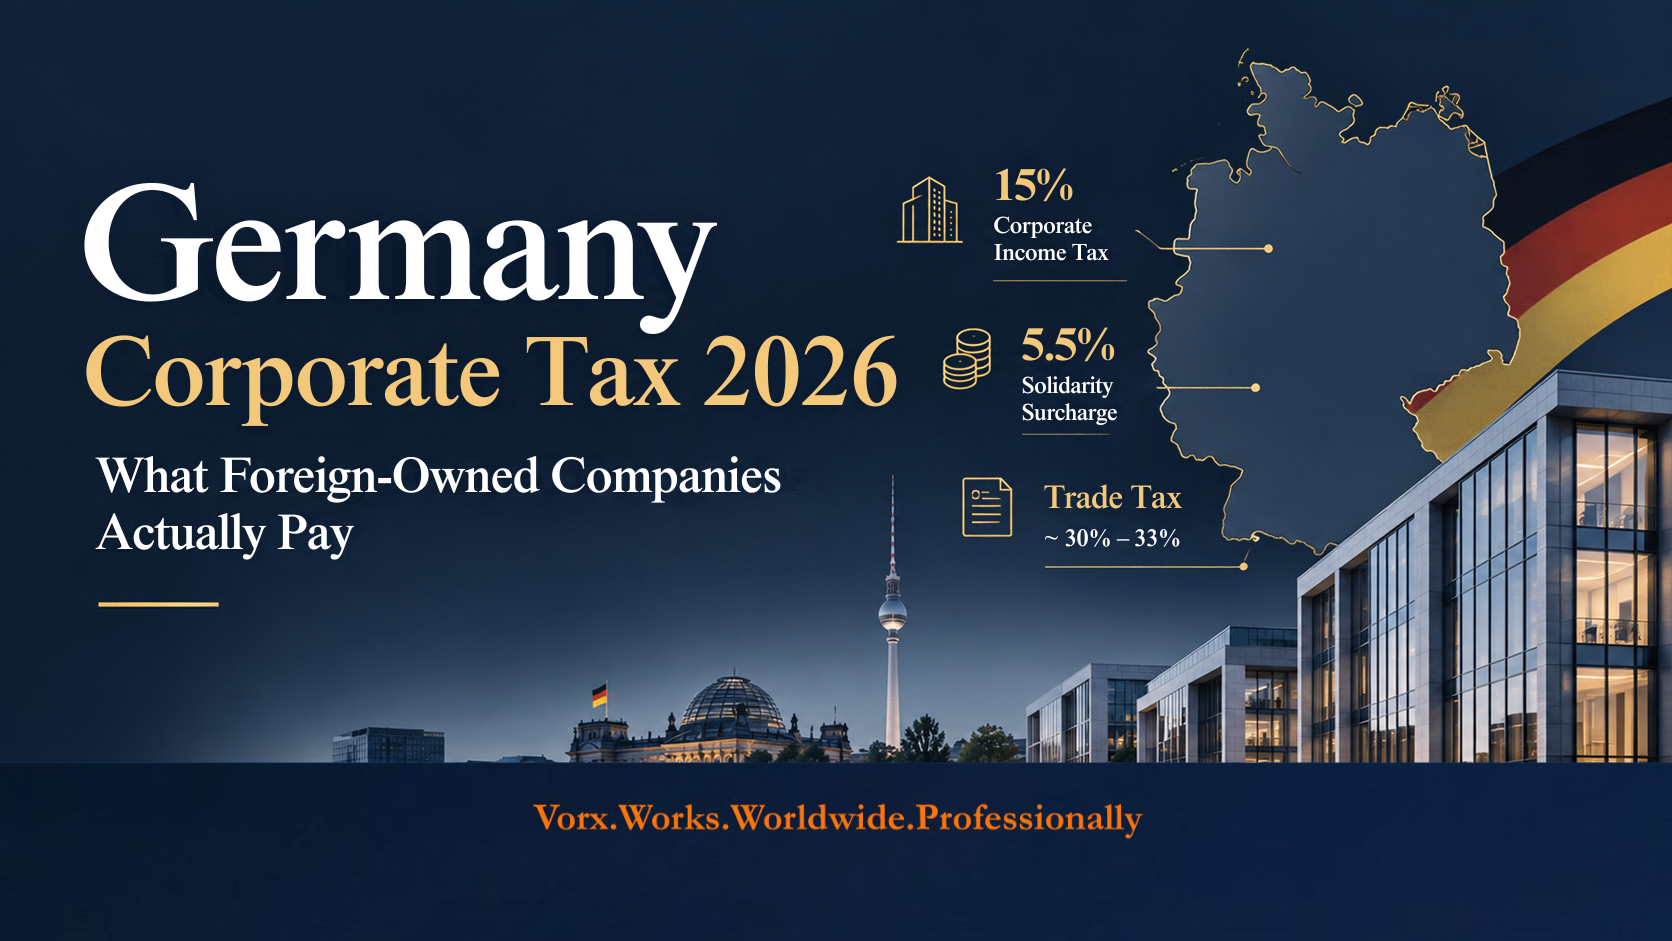
The tax bill is usually the first number they want. The short answer is that the Germany corporate tax rate in 2026 is 15% corporate income tax, plus a 5.5% solidarity surcharge on that tax, plus a local trade tax. Combined, most companies land between roughly 30% and 33%.
The details change that number, and so does a law that will start cutting the corporate rate from 2028. This guide walks through what applies to you, in plain language.
Key takeaways
- Corporate income tax is 15%, plus 5.5% solidarity surcharge on top (15.825% combined).
- Trade tax depends on the city, so the same profit is taxed differently in Munich and Berlin.
- Dividends sent to India face 10% German withholding under the treaty. Without treaty relief, the headline rate is 26.375%, which is generally reduced to about 15.825% once a partial refund is claimed.
- The corporate rate is scheduled to fall in steps from 2028, and the minimum trade tax rate rises from 2027.
Read this guide: Company Formation in Germany for Foreigners: Complete 2026 Guide.
What Is the Corporate Tax Rate in Germany in 2026?
Germany taxes company profits at three layers:
Tax | Rate | Notes |
Corporate income tax (Körperschaftsteuer) | 15% | Applies to GmbH, UG and AG |
Solidarity surcharge | 5.5% of the corporate tax | Works out to 0.825% of profit |
Trade tax (Gewerbesteuer) | 3.5% × local multiplier | Set by each municipality |
The same rules apply to foreign-owned and German-owned companies. The differences show up in withholding tax, transfer pricing and how you structure the business, which we cover below.
Who Pays German Corporate Tax, and on What Income?
It depends on where the company is based, not who owns it.
A company with its legal seat or place of management in Germany is taxed on worldwide income. A company without either is taxed only on German-source income, for example through a branch.
The place-of-management point catches people out. If an Indian parent actually runs its German subsidiary’s decisions from India, German authorities may look at where real control sits.
Day-to-day management by a German-resident managing director, with documented decisions, helps keep the picture clear.
Also note that a GmbH, UG or AG pays corporate tax itself. A partnership such as a GmbH and Co. KG is generally taxed at the partner level, though it still pays trade tax.
How Does Trade Tax Work, and Why Does Your City Matter?
Trade tax is where Germany’s effective rate really varies. The formula is 3.5% multiplied by the municipality’s Hebesatz (multiplier). A city with a 410% multiplier charges 14.35%, and one with 490% charges 17.15%.
Four points worth knowing:
Trade tax is not deductible as a business expense.
The €24,500 allowance applies to partnerships and sole proprietors, not to corporations. A GmbH pays trade tax from the first euro of profit.
Add-backs can raise your trade tax base. A portion of interest, rent, leasing and licence fees is added back to profit, so a heavily financed or rent-heavy company can pay more than the headline suggests.
The floor is rising. Until 2027 the minimum trade tax rate is 7%, and from 2027 onwards it becomes 9.8%. That corresponds to a minimum multiplier of 280% instead of 200%. It closes the door on setting up in a very low-multiplier town purely for tax reasons.
In any case, the trade tax office looks at where the business genuinely operates, not at a mailbox address.
Not sure what your German company could actually pay in tax?
Speak with Vorx to understand how company structure, location and cross-border ownership may affect your tax exposure.
What Does €1 Million of Profit Look Like in Practice?
Here is an illustrative example. Say an Indian-owned GmbH earns €1,000,000 of taxable profit. We assume no add-backs, no losses and no other adjustments.
| TAX | Munich | Berlin |
Trade tax | €171,500 | €143,500 |
Corporate tax (15%) | €150,000 | €150,000 |
Solidarity surcharge | €8,250 | €8,250 |
Total tax | €329,750 | €301,750 |
Profit after tax | €670,250 | €698,250 |
Now the parents in India want the money. A dividend triggers German withholding tax. The domestic headline rate is 25% plus solidarity surcharge, or 26.375%. Under the India-Germany tax treaty, the dividend rate is generally capped at 10%.
On the Munich dividend of €670,250, here is how it compares:
| TAX | Withholding on €670,250 |
Treaty rate (10%) | about €67,000 |
Domestic rate after partial refund (15.825%) | about €106,000 |
Domestic headline rate before any refund (26.375%) | about €177,000 |
Why three numbers? A foreign corporate shareholder can generally apply for a refund of part of the domestic withholding, which brings the effective domestic burden down to about 15.825%.
The treaty then reduces it further to 10%. So the treaty saves roughly €39,000 here, not €110,000.
The refund process takes time and paperwork, and anti-treaty-shopping and beneficial-owner rules apply, so confirm your position with the Federal Central Tax Office (BZSt) or a German tax advisor before planning cash flows.
The Indian parent can then generally claim a foreign tax credit against Indian tax on the same income.
This is typically done through Form 67 or its current equivalent under the Income-tax Act, 2025. Treaty percentages and Indian-side treatment should be confirmed with current texts and an Indian tax professional.
Is Germany Cutting Its Corporate Tax Rate?
Yes. Under legislation passed in 2025, the corporate income tax rate is scheduled to fall by one percentage point a year, from 15% to 10%, starting in 2028.
Trade tax does not change. The Federal Ministry of Finance states that the total burden on companies will then be just under 25% from 2032, compared with just under 30% today.
Year | CIT rate | Munich total | Berlin total |
2026 | 15% | about 32.98% | about 30.18% |
2028 | 14% | about 31.92% | about 29.12% |
2030 | 12% | about 29.81% | about 27.01% |
2032 | 10% | about 27.70% | about 24.90% |
The same package includes declining-balance depreciation of up to 30% on qualifying movable assets acquired within a set window (2025 to 2027), and an expanded research allowance.
For a company buying machinery, equipment or vehicles now, that can bring deductions forward.
A fair question is whether to delay profits or distributions until the rate drops. There is no universal answer.
It depends on cash needs, loss positions and parent-level taxation. Raise it with your advisor before making timing decisions, and confirm the final details in the Federal Law Gazette.
GmbH, Branch or Subsidiary: Which Is Better for Indian Companies?
Most Indian companies choose between a German subsidiary (usually a GmbH) and a branch.
GmbH (subsidiary) | Branch | |
Legal status | Separate German entity | Extension of the Indian company |
Taxed on | Worldwide income, as a German company | German-source income |
Liability | Generally limited to the GmbH | Indian company is directly liable |
Profit transfer | Dividend, with withholding | No dividend withholding on branch profits, but Indian-side rules apply |
A GmbH tends to be cleaner for liability and for customers who want to deal with a local company. A branch can look simpler on paper but leaves the Indian parent directly exposed.
There is also a risk many founders overlook: permanent establishment. If your employees, agents or contracting activities in Germany amount to a fixed place of business, German tax may apply even without a registered entity. Remote staff in Germany are a common trigger.
Choosing between a GmbH, branch or German subsidiary?
Vorx can help you evaluate the structure, tax implications, compliance requirements and cross-border setup before you register.
What Rules Catch Foreign-Owned Companies Out?
Most of these do not show in the headline rate.
Interest barrier (Zinsschranke): Interest deductions are capped relative to earnings, which matters if the subsidiary is funded by a parent loan.
Transfer pricing: Management fees, royalties, loans and service charges between you and your German company must follow arm’s-length terms and be documented.
A typical case: an Indian parent charges a flat management fee with no service records behind it. That invites questions.
Loss carryforward limits: Losses can be carried forward, but use is capped above a threshold, and a change in ownership can restrict them.
Participation exemption: When a German corporation receives dividends or share-sale gains from another company, 95% is generally exempt. This shapes holding structures.
Pillar Two: The global minimum tax applies only to groups with consolidated revenue of €750 million or more. If you are below that, it likely does not apply.
How Does VAT Work for Foreign-Owned Companies?
The standard VAT rate is 19% and the reduced rate is 7%. A German company needs a VAT ID, and filing frequency depends on your turnover and registration stage.
For Indian IT and service companies, the reverse charge mechanism on cross-border B2B services is often the practical issue: in many cases the German business customer, not you, accounts for the VAT.
Germany is also phasing in mandatory B2B e-invoicing, with receiving obligations already in place and issuing obligations rolling out in stages. Confirm the current timeline for your turnover level.
What Tax Incentives Exist?
Research allowance (Forschungszulage): a tax-based incentive for qualifying R&D, including personnel costs. Eligibility depends on certification and project type.
Degressive depreciation: available on movable assets in the window above.
Loss mechanics: carryforward with limits, plus a limited carryback.
Regional grants exist too, but those are non-tax programs with their own rules.
What Are the Filing and Compliance Requirements?
The tax year is normally the calendar year. New companies usually receive advance payment assessments, and these catch founders off guard. Tax is paid during the year on estimates, not in one lump after filing.
Returns are filed electronically through ELSTER. Deadlines are extended when a tax advisor files on your behalf.
You will deal with two identifiers, the tax number (issued by the local tax office) and the VAT ID (used in cross-border business). Keep books in line with German accounting rules and retain records for the statutory period.
A first-year rhythm for most founders looks like this: register the company, complete the tax office questionnaire, receive the tax number, apply for the VAT ID, register for payroll if you have staff, pay advance instalments on time, then file the first returns.
The mistakes we see most often are missed advance payments, VAT registration errors, late transfer pricing documentation and mixing personal and company expenses.
Already operating or planning to operate in Germany?
Get clarity on corporate tax, VAT, transfer pricing, filings and cross-border compliance with Vorx Consultancy.
Conclusion
Germany’s headline rate is straightforward, but the real tax cost depends on your city, your structure and how profits move back to India. Planning these early matters more than chasing the lowest number.
At Vorx Consultancy, we help Indian founders evaluate these choices before they commit, from entity structure to how the German and Indian sides fit together. For anything specific, speak with a qualified German tax advisor and an Indian tax professional.