There are a number of factors which have contributed to the rise in popularity of Italy among Indian businessmen and companies looking to venture into the European market.
These include the availability of manufacturing facilities, the fashion industry, and the opportunity to enter the EU single market.
But before any such company is incorporated, there is one question which looms large in the minds of most businessmen: what would be the tax burden of the company?
This guide walks through Italy’s corporate tax system in plain terms, with particular attention to what Indian-owned businesses need to know when a company operates across both jurisdictions.
Tax rules can change from year to year, so treat this as a starting point for planning rather than a substitute for advice tailored to your specific structure.
What Is the Corporate Tax Rate in Italy in 2026?
Italian companies are subject to two main taxes on profits. The first is IRES (Imposta sul Reddito delle Società), the national corporate income tax, charged at a flat 24 percent on net taxable profit.
The second is IRAP (Imposta Regionale sulle Attività Produttive), a regional tax on productive activity, typically around 3.9 percent, though this can vary depending on the region and, in a few cases, the industry.
There is also VAT (IVA) to account for, at a standard rate of 22 percent, with reduced rates of 10, 5, and 4 percent applying to specific categories of goods and services.
One point that often surprises founders: an Italian company that is tax resident is taxed on its worldwide income, while a non-resident entity, such as a branch, is only taxed on income sourced in Italy. This distinction affects planning decisions long before the first invoice is issued.
There are a few changes in the Budget Law of 2026 that should be noted, such as increased depreciation deductions for qualified investments and a lower threshold for participation exemption rules regarding dividends.
In case you are planning to invest in the shares of other corporations, then these changes should definitely be taken into consideration when making your decision.
Vorx Consultancy Insight: Founders sometimes compare Italy’s 24 percent IRES rate to lower-tax EU jurisdictions like Ireland or Poland without factoring in IRAP, social security costs and regional variation.
The comparison only makes sense once the full tax picture is on the table, not just the headline rate.
What Tax Obligations Apply to Foreign-Owned Companies in Italy?
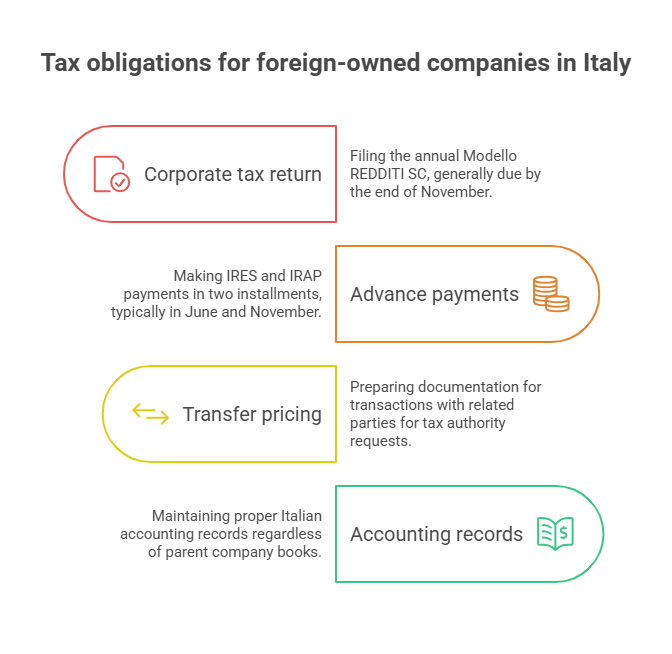
Once a company is registered and operating in Italy, a set of recurring obligations kicks in. These include:
- Filing the annual corporate tax return (Modello REDDITI SC), generally due by the end of November for the previous fiscal year.
- Making advance IRES and IRAP payments in two installments, typically in June and November.
- Preparing transfer pricing documentation for transactions with related parties, which must be available within a short window if requested by the tax authority.
- Maintaining proper Italian accounting records, even if the parent company keeps its own books elsewhere.
New companies usually calculate their first advance payment using a reduced method, since there is no prior year’s liability to reference.
Missing a deadline is not a minor issue in Italy. Penalties start at around 2 percent of the unpaid tax and can rise significantly for longer delays, with interest accruing on top.
Building a compliance calendar from day one is far less costly than catching up later.
Which Business Structure Works Best for Tax Purposes?
The entity you choose in Italy shapes how you’re taxed, how profits move back to India, and how much administrative overhead you take on.
The three most common options for foreign entrants are the SRL (limited liability company), a branch office, and a representative or liaison office.
Structure | Tax Treatment | Repatriation | Best For |
SRL | Italian tax resident | Dividends + withholding tax | Long-term business |
Branch | Taxed on Italian income | Direct profit remittance | Market entry |
Liaison Office | Generally no tax if non-commercial | Not applicable | Market research |
Planning to Set Up a Company in Italy?
Choosing the right structure can simplify your tax and compliance obligations. Talk to Vorx Consultancy about your Italy expansion plans.
Explore Your Italy Business Setup Options
A liaison office is often misunderstood. It can only carry out non-commercial activities such as market research or promotion.
The moment it starts generating revenue or signing contracts, it risks being treated as a permanent establishment, which brings full tax exposure with it.
This is one of the more common missteps we see among first-time entrants.
How Does the India-Italy Tax Treaty Affect Your Company?
This is where a lot of general guidance on Italian company tax falls short for Indian founders, because it stops at Italy’s domestic rules and doesn’t address what happens once income needs to cross back to India.
India and Italy have had a Double Taxation Avoidance Agreement in place since 1995. Its purpose is simple: to prevent the same profit from being taxed twice, once in Italy and again in India.
Profits earned from business activities are taxable in the country where there is a presence of a permanent establishment, and lower withholding rates may be applied to dividends, interest, royalties, and technical service fees between the two countries, unlike Italy’s regular withholding rates.
In order to avail of the above advantages under the treaty, an Indian company would require the issuance of a Tax Residency Certificate (TRC) by the Indian Income Tax department, which would be provided to the Italian tax authorities.
Otherwise, the normal domestic rate of withholding will apply, which can be significantly higher than the treaty rate.
A short example: An Indian software company sets up an Italian SRL to serve EU clients. When the SRL pays a management fee back to its Indian parent, the applicable withholding rate depends on whether a valid TRC has been submitted.
With the TRC, the treaty rate applies. Without it, Italy’s standard rate applies by default, and the difference is not trivial once volumes grow.
Vorx Consultancy Insight: For Indian entrepreneurs, treaty benefits are not automatic. They require paperwork, timing, and periodic renewal.
Building this into your compliance calendar from the outset avoids losing benefits simply due to a missed filing.
How Are Profits Taxed When Repatriated to India?
This is usually the question founders ask last, even though it should be asked early. When an Italian subsidiary pays dividends to its Indian parent, Italy applies withholding tax at either the treaty rate or the standard rate, depending on documentation.
Once that income reaches India, it becomes taxable there too, but Indian tax law allows a Foreign Tax Credit under Sections 90 and 91 for tax already paid in Italy, which reduces or eliminates the double taxation.
There’s also a regulatory layer that’s easy to overlook: setting up and holding a company abroad falls under India’s Overseas Direct Investment (ODI) framework, administered through RBI reporting requirements, including Form FC filings.
Expanding from India to Italy?
From India-Italy tax considerations to ODI reporting and profit repatriation, cross-border compliance needs to be planned from the beginning.
Speak With Vorx Consultancy About Your Italy Expansion
Founders who focus entirely on Italian compliance sometimes discover, later than they’d like, that the Indian reporting side needed attention too.
Fiscal year differences between the two countries may also lead to complexities in the Foreign Tax Credit process, which is why having your Italian and Indian tax processes on the same schedule becomes very helpful.
What Does an Annual Compliance Calendar Look Like?
For a typical Indian-owned SRL, the yearly rhythm generally includes:
- Incorporation and registration for a Codice Fiscale and Partita IVA
- Ongoing VAT filings, monthly or quarterly depending on turnover
- Advance IRES and IRAP payments around June and November
- Annual corporate tax return filing by the November deadline
- Transfer pricing documentation prepared and kept audit-ready
- TRC renewal to maintain treaty benefits
- RBI ODI reporting on the Indian side
These can be viewed as one combined schedule rather than an Italian schedule and an Indian schedule separately.
Read this guide: Italy Company Compliance Requirements: A 2026 Guide for Business Owners.
What Are the Common Mistakes Foreign Companies Make?
A few patterns show up repeatedly among first-time entrants:
- Assuming IRAP is a flat national rate, when regional variation and sector surcharges can change the actual figure
- Letting a liaison office drift into revenue-generating activity without realizing the tax consequences
- Missing TRC renewal and losing treaty-rate benefits as a result
- Underestimating INPS employer contribution costs when budgeting for local hires
- Treating Indian RBI and FEMA reporting as optional or secondary to Italian obligations
Most of these are avoidable with early planning rather than technical complexity.
The businesses that struggle are usually the ones that treated tax as a formality to handle after incorporation, rather than a factor in choosing the structure itself.
Need Help Setting Up Your Italian Business?
Vorx Consultancy helps Indian entrepreneurs navigate company formation, tax considerations, compliance, and cross-border business setup in Italy.
Conclusion
Italy’s tax system is manageable once you understand how the pieces fit together, but the real complexity for Indian entrepreneurs lies in the space between two jurisdictions rather than within either one alone.
Getting the entity structure, treaty documentation, and cross-border compliance calendar right from the start tends to save far more time and cost than fixing gaps after the fact.
At Vorx Consultancy, we work with Indian founders and investors to evaluate the right structure for Italian market entry, from initial entity selection through to ongoing compliance and repatriation planning.
Every business is different, and the right approach depends on your specific goals, so it’s worth discussing your situation before finalizing any structure.