Germany is the largest economy within the European Union, and for many Indian founders, it is the obvious first stop within Europe.
Incorporating the company is just half the work. At one point or another, you will need a German business bank account, and it’s here that many well-prepared founders find themselves losing weeks of valuable time.
A frequent story unfolds when the Indian SaaS founder already has his notarization and shareholder agreement ready, but finds out that the bank wants him to have the company registered to get an account opened while the registry requires evidence of the paid share capital. Neither side moves first.
The simple answer is that Indian citizens and firms owned by Indians can bank in Germany. It all depends on your status, where you come from, and how you verify yourself.
In this guide, I’ll cover all these aspects, as well as the question about the capital deposit that other guides ignore.
Can an Indian Entrepreneur Open a Business Bank Account in Germany?
In most cases, yes. There is no restriction on German nationality or residency for opening a bank account as a business owner in Germany.
The banks and authorized institutions have to carry out identification and KYC checks according to the German Law on the Fight against Money Laundering (GwG).
Your nationality does not matter much. It’s rather the ability to prove who the owner of the business is, what they do, and how they earn their money:
Your Situation | Possible? | Banking Option |
Indian founder with German GmbH/UG, living in India | Yes, with extra verification | Non-resident formation or business account |
Indian founder residing in Germany | Usually easier | Traditional or digital bank |
Indian company opening a German branch | Yes, with more documentation | Business account with parent company documents |
Freelancer in Germany | Yes, subject to bank requirements | Business or permitted current account |
Indian company without a German entity | Limited | Multi-currency account, potentially with a foreign IBAN |
Requirements vary by bank and by applicant, so treat this table as a starting point, not a promise.
What Documents Are Required?
Banks differ, but generally ask for similar things. It is useful to have all these things handy before starting, since missing files is one reason for delays.
Company documents
- Articles of association (Gesellschaftsvertrag), notarised
- Commercial register extract (Handelsregisterauszug), once the company is registered
- Transparency Register entry or beneficial owner (UBO) details
- German tax number or VAT ID, if you already have one
For each Indian shareholder and director
- Valid passport (OCI card holders should check what the provider accepts)
- Proof of residential address, such as a recent utility bill or bank statement
- Information on source of funds and source of wealth
- CV or professional background, which some banks request
If an Indian company is the shareholder or is opening a branch
- Certificate of incorporation and MOA/AOA
- Board resolution authorising the German entity or branch
- List of directors and shareholders, with ownership percentages
- Details of the ultimate beneficial owners behind the Indian company
Business information
- A short business plan or description
- Expected monthly turnover, main customers and countries involved
- Information about key suppliers
Opening a Business Bank Account in Germany?
Get professional guidance from Vorx on company formation, banking documentation and account-opening requirements.
Do Indian Documents Need an Apostille or Translation?
Indeed, often it is. The state of India signed the Apostille Convention from the Hague, therefore, the process of legalization is done via apostille.
In India, this is handled through the MEA Process. Verify the procedure beforehand since laws may be subject to change.
Some tips to consider:
Types of documents: Corporate documents, POA, and some other certificates issued in India are likely to require an apostille for the use with a German notary, registry, or bank.
Translation: German government agencies usually operate in German language. In case of a non-German document, a translator (beeidigter Übersetzer) is likely to be required.
Some digital providers accept English documents. The traditional banks and the commercial registry are stricter.
Make sure to get additional copies: It often turns out to be too late when founders understand that the bank, notary, and registry need an original each.
It is more cost-effective to have two or three apostilled copies from the very beginning.
Double-check all names: They should coincide in the passport, apostilled document, and notary deed.
It is enough to miss a middle name or write it differently.
A founder we will call Rahul (an illustrative example, not a real client) had his board resolution apostilled before the company’s name was finalised.
When the registry required a slightly different company name, the resolution had to be redone, which cost him about three weeks. Locking down names and structure before you apostille anything saves real time.
What Is the GmbH and UG Capital Deposit Problem?
This is the issue that catches most foreign founders.
Share capital of GmbH should not be less than €25,000. At the time of incorporation, not less than €12,500 should be subscribed to the share capital.
For a limited liability company to become operational, share capital can be €1 only. It should be entirely subscribed to prior to registration. Always confirm the current contribution rules with your notary.
The catch is that the money must go into a company account that does not legally exist yet. That is why Gründungskonto (formation account) products exist.
These are bank accounts that are opened for an existing company that is under development, allowing you to contribute funds and receive proof of your deposit for registration.
The typical order follows in this manner:
- Notary prepares and certifies the formation documents.
- You open a formation account with a provider that offers one.
- Share capital is transferred in and the provider issues confirmation of payment.
- The notary files the registration with the commercial register.
- The company is registered and you receive the commercial register extract.
- You upgrade to, or open, the full business account.
Two practical points for Indian founders. First, transferring capital from India involves Indian regulatory steps, which we cover below.
Start those early, since the bank-to-bank transfer can only happen once the German account is ready. Second, the transfer must come from the right source.
Banks generally expect the capital to come from the shareholder’s own account, and payments from third parties can raise questions.
Can You Open the Account Remotely?
Usually yes, but it is identity verification where Indian founders struggle.
Digital service providers will use VideoIdent, which is essentially a live video call with an agent.
The traditional banks will ask you to come to the branch, and it needs to be planned around your notary appointment, making it one single journey. The PostIdent (German post offices) works only when you are in Germany.
Before scheduling the call, there are three things that need to be done – passport with six months validity period, matching the name with the company documents, and latest address proof. Agents usually follow German timings, so expect a night call from India.
I made a mention of the power of attorney and managing director. Should I make this part of the document?
Read this Guide: Germany Corporate Tax Guide in 2026.
Should You Choose a Traditional Bank or a Digital Business Bank?
There is no single best answer. It depends on what you need first.
Feature | Traditional Banks | Digital Banks & Fintechs |
Non-resident access | Stricter requirements | Often more flexible |
Account opening | Usually slower | Usually faster |
IBAN | German (DE) | Depends on provider |
Fees | Often higher | Usually lower or plan-based |
Accounting tools | Varies by bank | Often integrated |
Loans & credit | More options | Limited options |
Deposit protection | Statutory bank protection | Depends on provider and licence |
The final line requires some elaboration. While a fintech with an e-money or payments license is regulated, your funds would be protected by safeguarding regulations and not a deposit guarantee system.
Both systems are not necessarily dangerous, although they are different, so you should refer to the disclosures of the provider.
The IBAN row matters too. Some providers issue an IBAN from another EU country. That works for many purposes, but it can create friction with certain direct debits, some payroll processes and some customers.
If your tax advisor or customers need a German IBAN, confirm it before you commit.
How Does the Application Process Work?
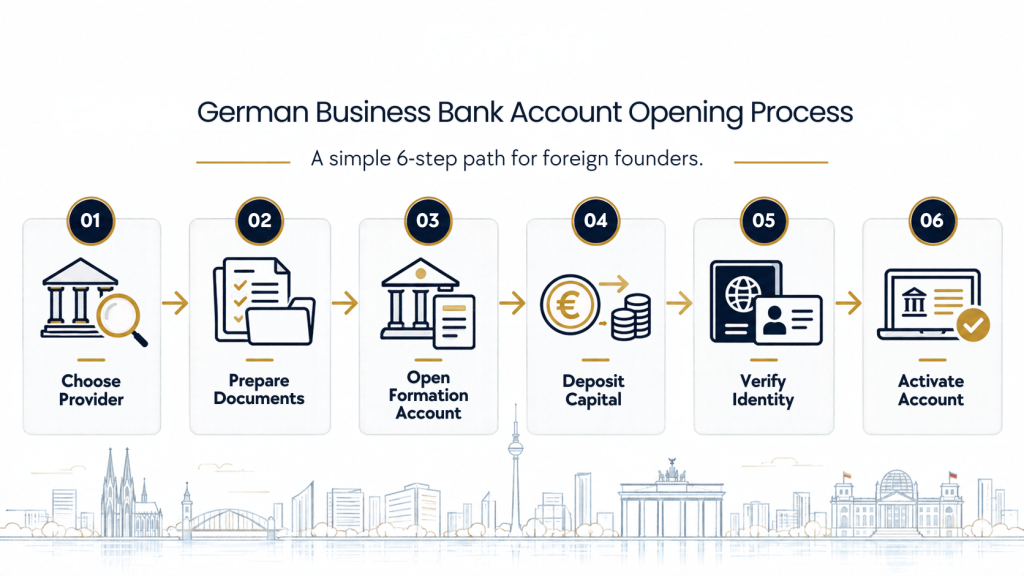
Here is the typical flow for an Indian founder forming a GmbH or UG.
Choose the right business structure and banking route: For GmbH, UG, subsidiary, or sole proprietorship you will need different documents.
Find an agency that serves foreign founders: Find out if they serve Indian founders and formation accounts.
Arrange for apostilling of the documents: Do this after company names and structure are final.
Open the formation account if you are forming a GmbH or UG.
Transfer the share capital and obtain proof of payment.
Complete the notary and commercial register steps.
Apply for the full business account using the registered company documents.
Get your ID verified through video, post office, or branch visits.
Provide responses to KYC queries promptly.
Open your account, cards, online banking, and link your accounting services.
It all seems very easy on paper: But most of the delays occur when you reach step 3 (documents) and step 9 (no responses to follow-up queries).
Read this guide: Company Formation in Germany for Foreigners: Complete 2026 Guide
Why Do Business Bank Account Applications Get Rejected?
German banks have to observe very stringent money laundering laws. They are allowed to refuse any services to someone if they cannot comprehend the nature of the business or establish its ownership regardless of the owner’s integrity.
The most common reasons we see:
Ambiguous business model: Stating “consulting and trading” is insufficiently specific for the bank to understand.
Insufficient details on ownership: Missing data on the UBO, or no entry in the Transparency Register matching the documents.
Unexplained sources of funds: Particularly important regarding bigger amounts of money.
More risky industries: Cryptocurrency, some kinds of trading, and some intermediaries are under greater scrutiny.
Inconsistent documentation: Discrepancies between names, addresses, or numbers of owners in different documents.
No visible German ties: Providers sometimes look for a local presence, customer base or tax advisor.
If you are declined, don’t immediately apply to five more providers. Whenever possible, find out the cause and solve the problem, then reapply, possibly using a new type of material. Multiple applications within a short time frame may appear odd.
Avoid Unnecessary Banking Delays in Germany
Vorx helps Indian entrepreneurs prepare their company documentation and navigate business banking requirements.
What Indian Regulatory and Tax Points Should You Plan For?
This is the aspect that is mostly ignored by most guides. This is general information and not tax or legal advice. Consult your chartered accountant (CA) to know the current regulations.
Outward Remittance: Individuals can utilize the Liberalized Remittance Scheme (LRS) in its annual limit for permissible purposes.
Investment in a foreign company from India: The regulations for investment in a foreign company will follow the overseas investment regulations under FEMA. Whether it would be done as an individual investor or an Indian company needs to be determined before remitting any money.
Report: Investments in foreign companies and foreign bank accounts will need reporting wherever required and in your income tax return (eg: schedule FA).
Double Taxation Agreement: There is a Double Taxation Avoidance Agreement between India and Germany. How it will operate will depend on where you are a resident and from where you earn your income.
Permanent Establishment (PE): If an Indian company establishes itself in Germany even in the form of a branch, then Germany might have some taxation obligation.
Exchange of Financial Account Information: India and Germany exchange financial account information under the Common Reporting Standard. Therefore, proper reporting becomes important.
Conclusion: It is always better to consult with your Indian CA and German Steuerberater. If the transfer is correct in Germany but wrong in FEMA, it will create complications in future.
How Can Vorx Consultancy Help?
At Vorx Consultancy, we assist in setting up businesses and planning banking for Indian entrepreneurs and foreign investors in Germany.
This often involves deciding on the most appropriate structure for the business, organizing documentation, coordination with notaries and tax consultants, as well as presenting the business idea to the banks in an organized way.
While we do not guarantee any approval by the bank since the bank decides whether to approve or not, a proper business presentation will facilitate that process for the bank.
Final Thoughts
It is not the application itself that poses the biggest challenge in opening a bank account for your company in Germany but rather providing the following details in the correct order: legal entity, consistency in documentation, capital flow from India, and finally, a description of your business for the compliance officer.
If you are unsure which legal form to choose – GmbH or UG – or whether the path you chose fits into the process of obtaining the banking services, it may be good to start with this step.
Ready to Establish Your Business in Germany?
From company formation to banking documentation and compliance guidance, Vorx supports your German business expansion.