Your Hungarian Kft is registered, or about to be. On paper the company exists, but it can’t really trade until it has a bank account, and for foreign founders this is where timelines usually slip.
Opening a Hungary business bank account isn’t legally complicated. What makes it hard is that banks layer their own due-diligence standards on top of the law, and those standards weigh heavily on non-resident directors.
This guide separates the two: what Hungarian law actually requires, and what banks will expect from you. It’s written with Indian and other non-EU founders in mind, but most of it applies to any foreign owner of a Hungarian company.
Is a Hungarian Business Bank Account Mandatory?
Yes. Hungary’s Act on the Rules of Taxation (Act CL of 2017) requires every domestic legal entity, including a Kft, to hold at least one domestic payment account (pénzforgalmi számla).
The first one must be opened within 15 days of the company receiving its tax number.
That rule has two practical consequences:
The account must be held with a financial institution operating in Hungary: A bank account in Dubai, London or Mumbai doesn’t satisfy it on its own.
Company money should move through payment accounts: Apart from payments that can lawfully be made in cash, the company is expected to keep its funds and run its transactions through these accounts.
What about accounts outside Hungary?
You can keep them. Plenty of Kfts hold EUR accounts elsewhere. However, the company must report foreign payment accounts to NAV, the Hungarian tax authority, including the bank’s name, the account number and the opening and closing dates, generally within 15 days. Your accountant normally files this, so make sure they know every account exists.
Do you need to deposit share capital first?
The minimum registered capital for a Kft is HUF 3 million. Unlike some jurisdictions, Hungary doesn’t require you to lock that amount into a blocked account before registration.
The deadline for paying in the cash contribution is set in your deed of foundation, within the limits of the Civil Code, so confirm your exact deadline with the lawyer handling your incorporation. In practice, transferring the capital is often the account’s first transaction.
Can a Non-Resident Director Open a Corporate Bank Account in Hungary?
Legally, yes. Hungarian company law doesn’t require a Kft’s managing director to live in Hungary or even in the EU, and foreign individuals or companies can own 100% of a Kft.
The friction comes from the bank. Under Hungary’s anti-money-laundering rules, banks must identify the company’s representatives and beneficial owners and understand the purpose of the business relationship. Each bank decides how it does that.
In practice:
- Most traditional banks prefer, and many insist on, the managing director or authorised signatory attending a branch for identification and signing.
- Some banks accept video identification for certain profiles, but this is decided case by case and can be much slower.
- Banks are noticeably more cautious with companies that have no visible link to Hungary: no local customers, staff, office or director.
So “Can I do this remotely?” isn’t a yes-or-no question about Hungary. It’s a question for a specific bank about your specific profile.
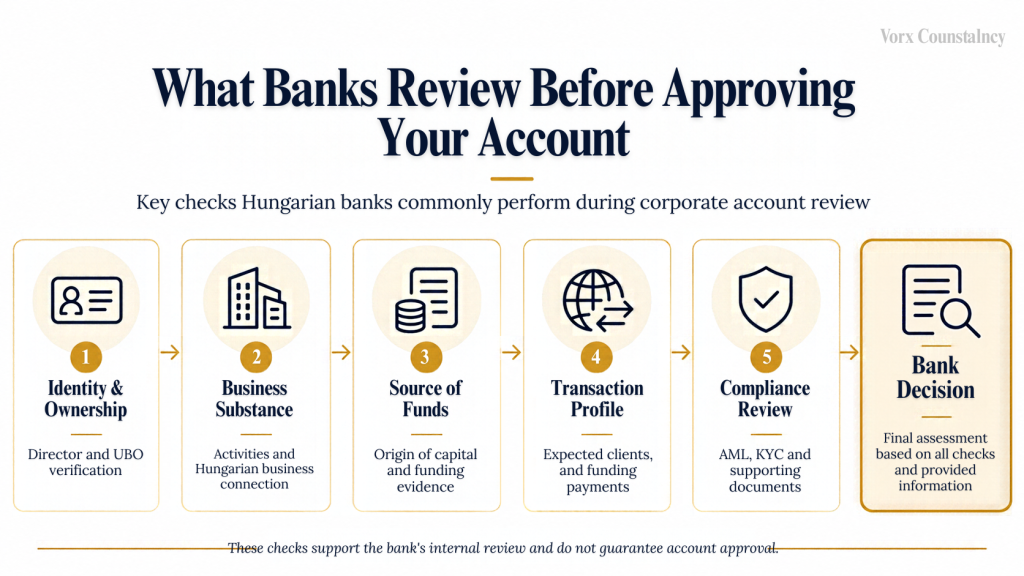
Documents Hungarian Banks Usually Ask For
Exact lists vary by bank, ownership structure and industry, but expect something close to this:
Category | Required Documents | Notes |
Company | Registry extract, incorporation deed, director’s signature, tax number | Usually issued in Hungarian |
Directors & Owners | Passport, address proof, UBO and PEP declarations | Translation or apostille may be needed |
Corporate Shareholders | Incorporation certificate, ownership records, good-standing certificate | Certification may be required |
Business Profile | Business activities, expected transactions, client details, contracts | Important for KYC |
Source of Funds | Bank statements, tax returns, investment records | Must explain funding origin |
For Indian founders:India and Hungary are signatories to the Apostille Treaty, so Indian documents usually get apostilled at the Ministry of External Affairs rather than legalised at an embassy.
Before even getting started, make sure that the bank accepts documents in English or requires certified Hungarian translations of the same. One simple question can save you weeks of time.
Have doubts about your documents? Have Vorx review your corporate and individual documents prior to visiting any bank.
Unsure If Your Banking Documents Are Ready?
Vorx Consultancy helps foreign entrepreneurs review company documents, ownership details and KYC requirements before approaching Hungarian banks.
How to Open a Business Bank Account in Hungary: Step by Step
Short-list banks that match your profile: The larger banks in Hungary are OTP, K&H, Erste, Raiffeisen, MBH, UniCredit, and CIB.
Compare English language support, multi-currency support, internet banking, and most importantly, their willingness to work with foreign-owned firms in your industry.
Do pre-screening before traveling: Send a brief profile of the company, its ownership, and anticipated activities. It’s better to have an immediate “no” than to be rejected after having traveled there.
Prepare and verify documents: Get apostille, translated and cross-checked for any discrepancies regarding name, date, or address on all documents.
Attend the identification meeting: Either in person at a branch office or via video if the bank allows for it according to your profile.
Respond promptly to further questions: This could be from the compliance department with regards to your clients, contracts, and financing. A delayed response to such questions is a frequent reason why the file gets held up.
Open the account: The account number, internet banking, and cards get issued.
Involve your tax advisor: They will confirm that the account has been properly registered at NAV, including other foreign accounts.
Loop in your accountant: They’ll confirm the account is properly registered with NAV and that foreign accounts are reported.
How long does it take? There’s no official timeline. A straightforward application with the director attending in person can be completed in days.
Remote or complex cases can run for months. One corporate service provider has published a case where a fully remote opening took about seven months.
Read this guide: Hungary Company Formation for Foreigners Guide in 2026.
Traditional Bank or Digital Provider?
Many founders ask whether they can skip the branch visit and use fintech instead. The answer depends on what you need the account to do.
Factor | Traditional Bank | Digital Provider |
Local Account Requirement | Generally meets | Confirm eligibility |
Account Opening | Often in person | Usually online |
HUF Payments & Taxes | Supported | Varies |
Multi-Currency | Available; fees vary | Often lower-cost |
Loans & Credit | Available, subject to approval | Limited |
Foreign-Owned Companies | Strict KYC | Eligibility restrictions |
The landscape is shifting. The Hungarian central bank licensed the operation of Revolut’s Hungarian branch at the end of 2025, and now Revolut is gradually switching Hungarian clients to their Hungarian (HU) IBANs throughout 2026.
However, since Wise caters to EU business customers via its Belgian company, a Wise account will most likely be considered an off-shore account and will need to be declared.
Before you entrust a fintech company with your firm’s only bank account, consult your accountant whether it is a domestic payment account.
A typical arrangement involves using a regular Hungarian bank for HUF accounts, taxes, and payroll, as well as a digital one for foreign currency collection.
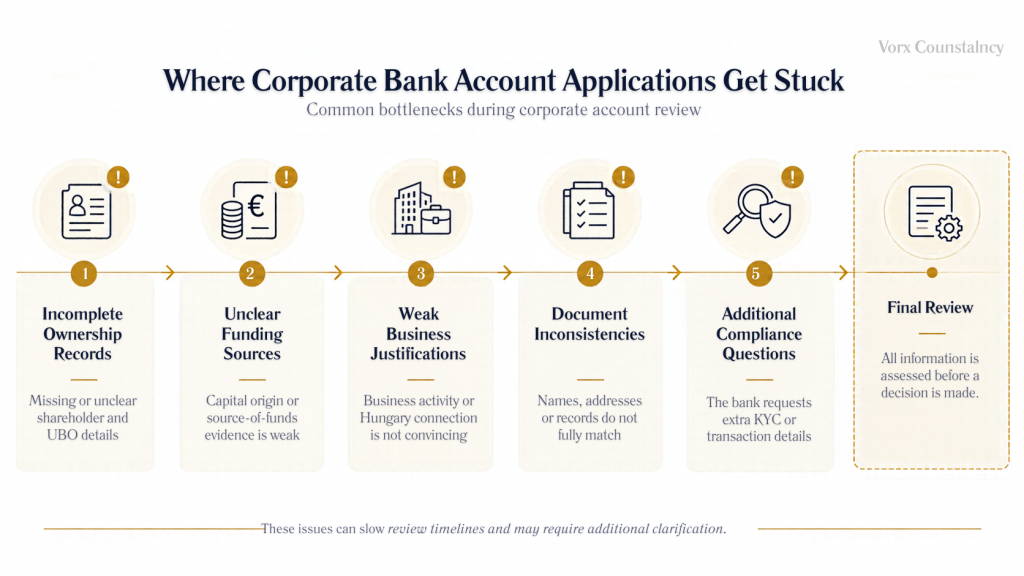
Why Applications Get Delayed or Rejected
Although banks do not specify reasons, certain factors keep reoccurring:
Vague business model: “Consulting” or “trading” without any names of customers, goods or even countries mentioned.
No relation to Hungary: Nothing shows why this company is located in Hungary.
Riskier operations: Crypto, gambling, payment processing and some types of commodity trading fall under additional scrutiny.
Unclear source of funds: Capital arriving from third parties or accounts the founder can’t explain.
Inconsistent paperwork: Different spellings of a name, or old addresses on some documents.
Complex or opaque ownership: Layered holding companies or nominee arrangements without clear beneficial-owner documentation.
Example (hypothetical): Riya, a SaaS founder in Bengaluru, sets up a Kft to sell to EU clients. Her first application describes the business in one line, and the capital arrives from a relative’s account.
The bank pauses the file. On her second attempt she submits a client pipeline, her pricing model and her ODI paperwork showing the funds came from her own account through an authorised Indian bank. The review moves forward without further questions.
If you’d like a second opinion on which banks suit your sector and ownership structure, Vorx’s corporate bank account opening support starts with exactly that assessment.
Avoid Common Banking Application Delays
From bank selection to KYC preparation, Vorx Consultancy helps foreign-owned businesses prepare for Hungary’s corporate banking requirements.
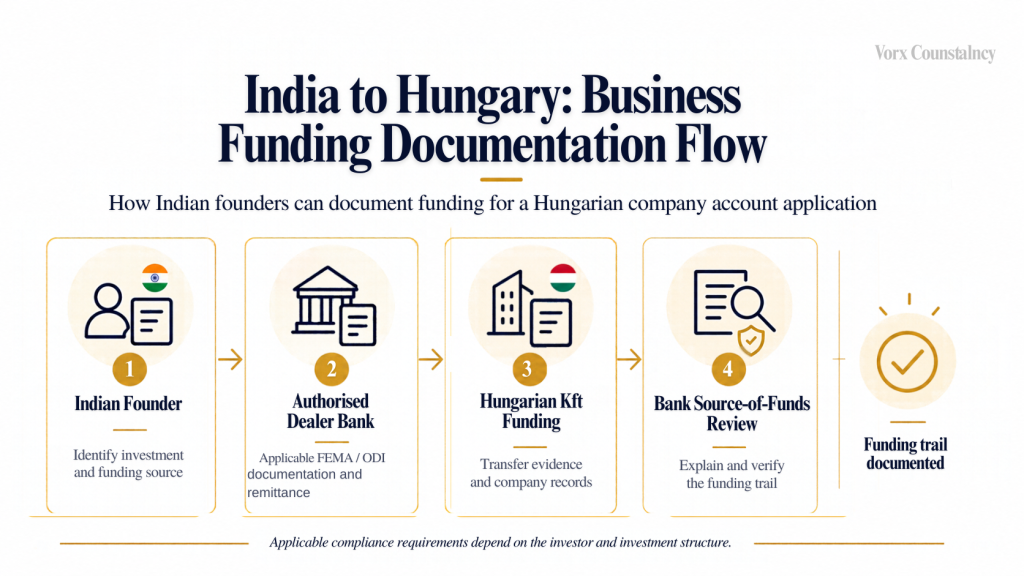
Extra Points for Indian Founders
Properly fund the Kft: Overseas Direct Investment under FEMA rules means that the investment needs to be done through your authorized dealer bank with proper filings. The amount invested by individuals is covered under the Liberalized Remittance Scheme limit of USD 250,000 per financial year.
This will have a double benefit: firstly, you remain compliant in India; secondly, this documentation serves the purpose of Source of Funds for the bank in Hungary. Vorx’s team of ODI and FEMA experts can assist you here.
Consider the place of management: If the Kft is effectively managed in India, then tax residence of Kft may be questioned under India’s Place-of-Effective Management provisions. Please take professional advice before entering into trade.
Time planning: The 15 days period starts from the issuance of the tax number. Get bank pre-checking scheduled at the same time as company incorporation, and not afterwards.
After the Account Opens
Ensure that all corporate income, expenditure, tax payments, and salaries are processed through corporate accounts.
Promptly notify the bank regarding any opening of foreign accounts.
Be prepared for periodic KYC reviews, and respond immediately; non-compliance can result in restrictions.
Inform the bank of changes to your business activity to ensure that your profile is up-to-date.
Good accounting and bookkeeping makes most of this routine.
Read this guide: Hungary Corporate Tax 2026
Your Next Step
Opening a business bank account in Hungary all boils down to one criterion, as per the law, where you have to establish your domestic bank account within 15 days, although it is up to the bank how difficult it can make this process for you.
Entrepreneurs who have already prepared their business profile and have their documents in order along with sources of money will face less difficulty compared to others.
If you’re planning a Hungarian company, or already have one and are stuck at the bank, book a consultation with Vorx.
Your profile will be reviewed, banks that suit you will be shortlisted and the paperwork will be taken care of. The approval depends on the bank, however a well-prepared application is what can help you get the maximum chances of success.
Ready to Open Your Hungary Business Bank Account?
Vorx Consultancy assists foreign entrepreneurs with banking requirements, document preparation and application guidance. Let our team help you plan your next step.